


Warehousing Real Estate in the MMR : The Quiet Growth Engine Developers Overlook
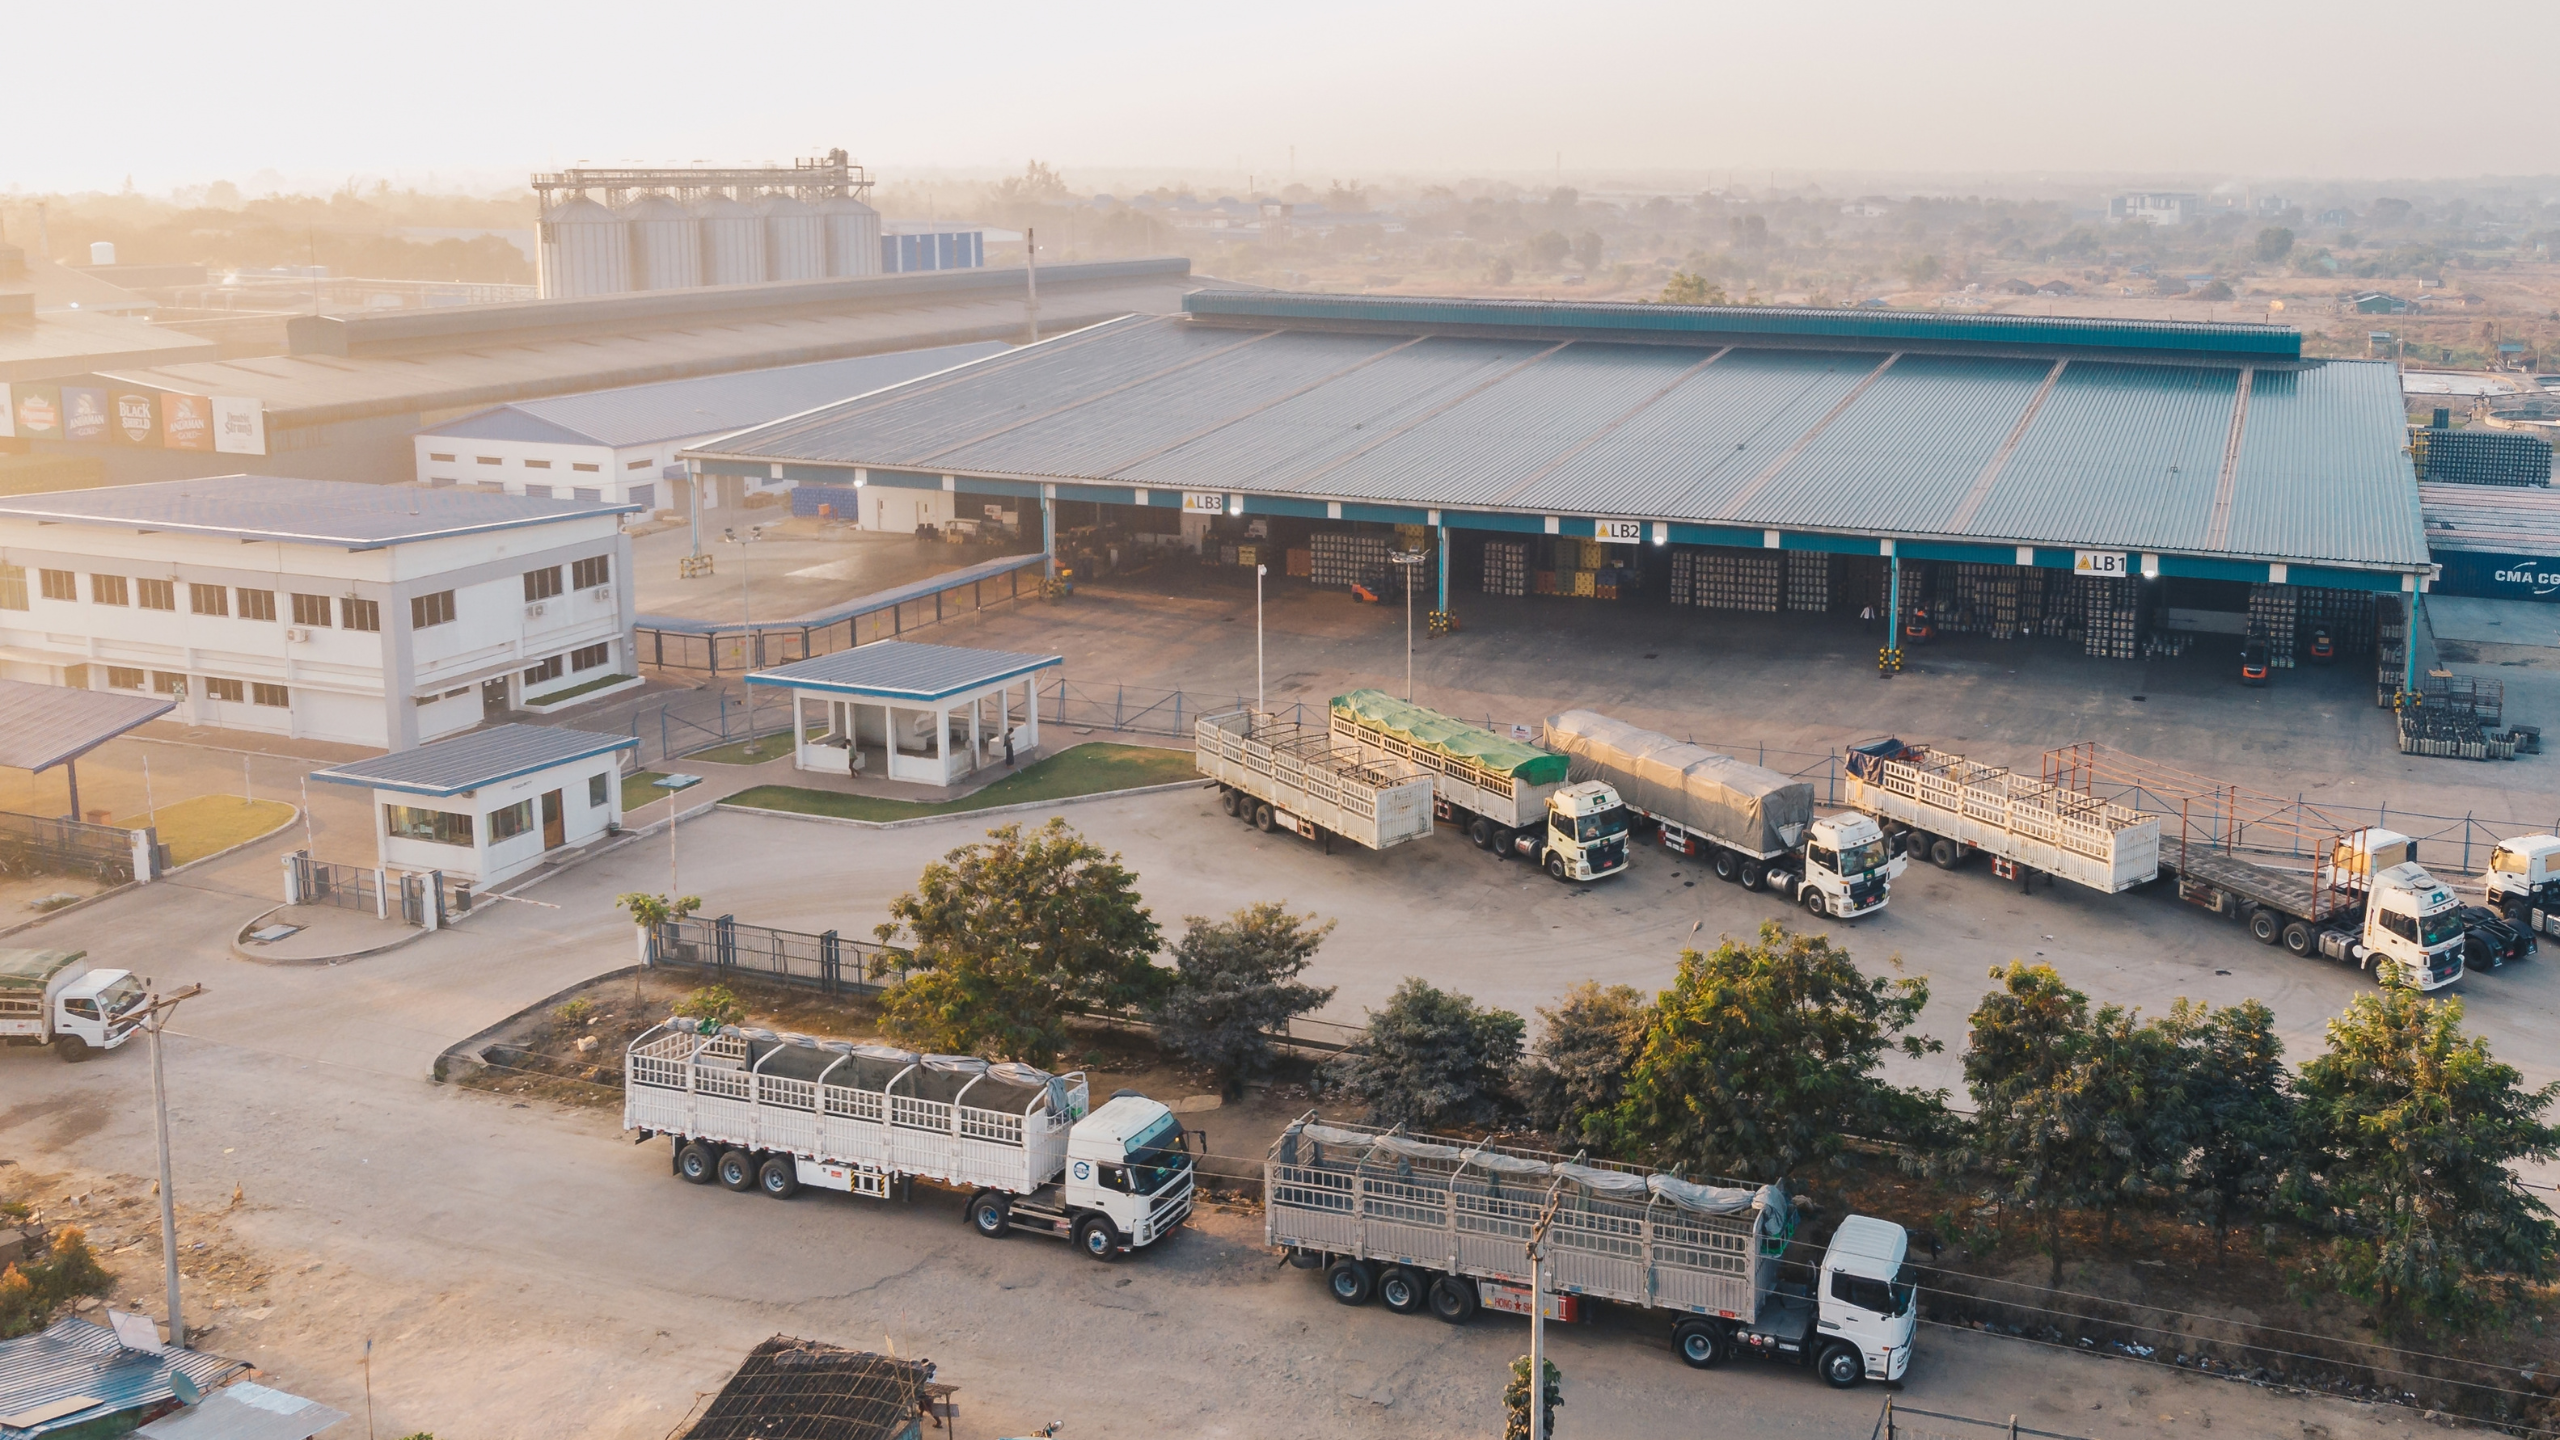
While attention stays fixed on apartments in the western suburbs and towers in South Mumbai, the fastest tightening real estate market in the region is warehousing. In the first half of 2026, the MMR recorded 6.6 million square feet of Grade A warehouse demand against just 3.5 million square feet of new supply, a demand to supply ratio of about 1.9 times. Nationally, Grade A demand outpaced new supply, and western India, led by Mumbai and Pune, drove roughly 65 percent of second quarter absorption. For a developer willing to look beyond residential, logistics is where demand is structurally outrunning supply, and that is exactly the condition that produces pricing power.
The headline yields, the longest lease tenures and the most durable demand tailwinds in Indian real estate are increasingly found in a Grade A shed, not a show flat.
This is not a speculative call. It is what the absorption data has been saying quarter after quarter.
How strong is warehousing demand in the MMR?
Strong, and concentrated. The MMR’s 1.9 times demand to supply ratio in the first half of 2026 is among the tightest of any real estate segment in the region, and Mumbai has emerged as the country’s largest warehousing contributor, posting around 5 million square feet of absorption in a single quarter with dramatic annual growth. Within the region, Bhiwandi dominates, accounting for the overwhelming majority of the city’s warehouse leasing, followed at a distance by Panvel, Navi Mumbai, Kalyan and Thane.
The demand is broad based rather than reliant on one sector. Third party logistics operators are the largest occupiers, taking around 41 percent of leasing nationally, followed by consumer goods and engineering and manufacturing tenants. Add e-commerce and quick commerce, which are growing their footprint fast, and the demand base is diversified enough to be durable.
What is driving the warehousing boom?
Several forces are compounding at once. E-commerce and quick commerce need dense, well located fulfilment space near consumption centres. Third party logistics providers are consolidating scattered small warehouses into larger, more efficient Grade A facilities. Manufacturing is expanding on the back of the China Plus One shift in global supply chains. And the data centre boom along the same corridors is generating ancillary demand for supporting logistics and infrastructure.
Layered on top is a quality upgrade. Occupiers are moving from old, informal sheds into Grade A space with better specifications, and demand for green certified warehouses is rising as large occupiers apply sustainability standards. This is the same premiumisation story playing out in offices and homes, now arriving in logistics, and it rewards developers who build to modern specification rather than the lowest cost.
Why should a residential developer look at warehousing?
Because the risk and return profile is genuinely different, and complementary. Warehousing offers longer lease tenures, institutional tenants, and healthy rental yields, commonly cited around 8 percent and above for quality commercial and industrial assets, which is materially higher than residential rental yields. For a developer whose balance sheet is concentrated in the long, capital intensive cycle of residential development, a logistics asset can add a steadier, income generating counterweight.
The entry points are more flexible than they once were too. Beyond building large format Grade A parks, developers can pursue pre leased industrial units in organised parks, land plays in the Bhiwandi and Panvel belts where values have held firm even in softer leasing quarters, and increasingly, structured exits through REITs and SM REITs that have opened institutional capital to the sector. Working out which of these fits your capital and your appetite is a strategy and positioning decision before it is a construction one.